Nvidia is putting $3 billion into Meta's stock offering. Meta, in the same breath, announced it will buy more Nvidia hardware for its next generation of AI agents. If that sounds like the same money making a round trip, that's because it basically is — and if your infrastructure plans rest on the idea that hyperscaler AI spending reflects genuine end-market demand, this week's news should make you uncomfortable.
The Decoder reported today that Nvidia is investing $3 billion in Meta's planned equity offering, citing the Wall Street Journal. The two companies also said they would expand their partnership around Meta's AI product Muse, with Meta planning to deploy Nvidia's Vera Rubin systems and Vera CPUs for its next wave of AI agents. AMD and Broadcom have also expressed nonbinding interest in buying up to $5 billion in Meta shares combined, according to the same report — though it's worth noting that whether Nvidia's $3 billion sits inside or outside that $5 billion figure is not fully clear from the sources.
The fundraising itself is enormous. The Guardian reported that Meta wants to raise up to $95 billion through a two-part offering: $35 billion in underwritten stock sales and a $60 billion at-the-market offering of new Class C shares, which carry no voting rights — meaning Mark Zuckerberg's control of the company stays intact. The Decoder's second report broke the $35 billion portion down further: $22.5 billion in Class A common stock and $12.5 billion in depositary shares that convert to common stock in August 2029. The Class C at-the-market sales aren't expected to start before the first quarter of 2027.
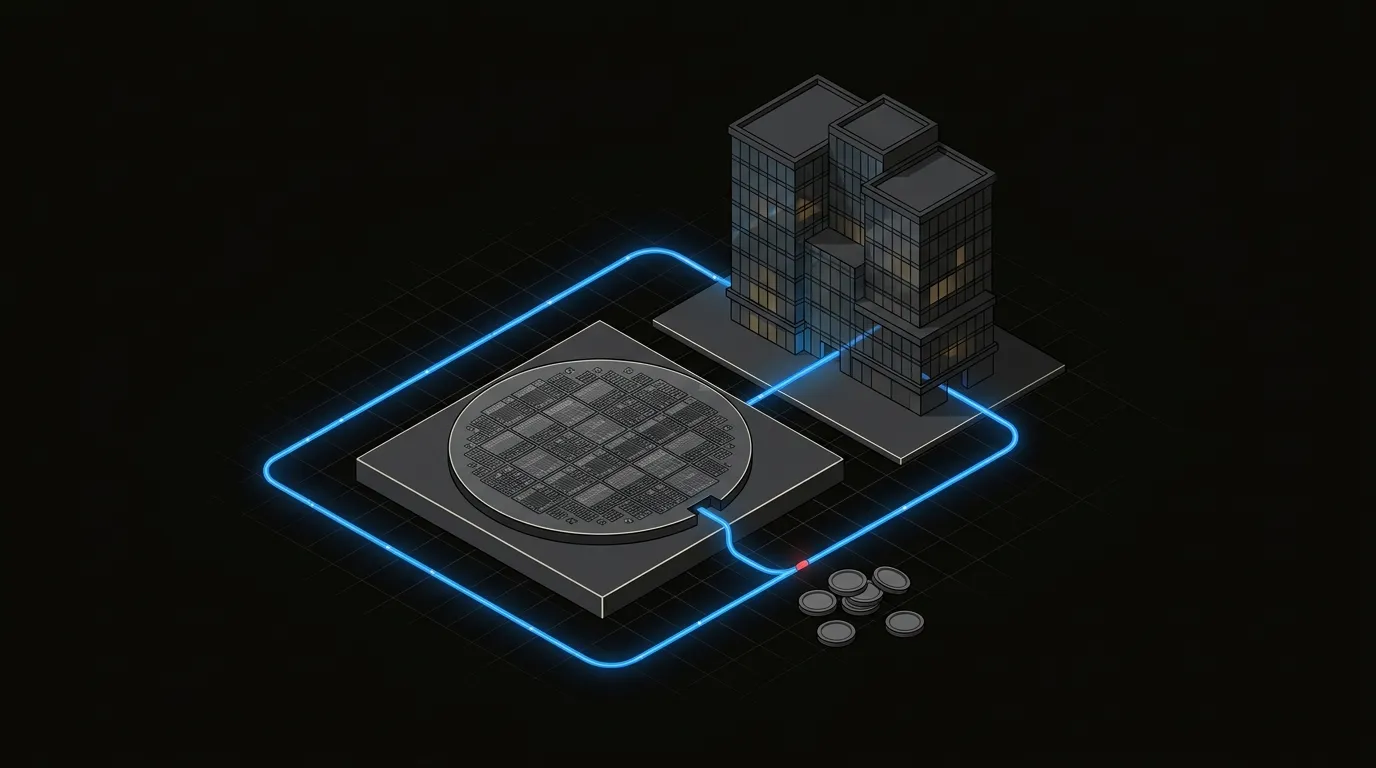
The loop critics are pointing at
The circular financing concern isn't new. Critics have flagged the same pattern with Nvidia's investment in OpenAI: a chipmaker buys equity in a customer, the customer uses the capital to buy chips, and the chipmaker books revenue. The Decoder noted that critics warn this structure 'could hide how much real demand exists.' That's the polite version. The blunter version: it's possible to manufacture the appearance of massive AI infrastructure demand by recycling money between suppliers and their biggest customers, and the financial press will report each transaction as evidence of AI's unstoppable momentum.
To be fair, the bull case is straightforward. Meta is a company with real revenue, real users, and real products that depend on inference at scale. It's not a speculative neocloud borrowing against future contracts. Neil Wilson, an analyst at Saxo UK, made exactly this point to The Guardian: 'Meta's not going to struggle to service debts and can lean on equity raises to minimise debt too.' Meta spending on Nvidia chips isn't fake demand — Meta actually needs compute. The question isn't whether this particular purchase order is real. It's whether the circular structure inflates the signal that others use to size their own bets.
And that's where I hold the take. When a chipmaker funds the customer who then buys the chips, the resulting revenue figure gets cited by analysts, repeated in earnings calls, and used by mid-market companies to justify their own infrastructure investments. The demand signal travels downstream and looks clean by the time it reaches a VP of Engineering deciding whether to lock in a multi-year cloud GPU contract. It isn't clean.
The neocloud stress fractures make it worse
The same week this deal dropped, the rest of the AI infrastructure market sent a very different signal. Elon Musk wrote on X Sunday that debt markets had 'almost entirely shut off access to money for any company that doesn't have substantial revenue independent of AI data centers,' and predicted 'guppy-level death and consolidation' among more than 200 neocloud firms. He was responding to venture capitalist Chamath Palihapitiya, who had described neoclouds as 'disorganized and poorly capitalized.' Shares in CoreWeave fell 2.7% and Iren was expected to fall 2.2% in premarket trading Monday after those comments.
CoreWeave's CEO Michael Intrator, according to Bloomberg as reported by The Guardian, sent an internal memo to employees saying some investors had misunderstood the company, and that its stock had declined more than a third over the past month. CoreWeave carries approximately $35 billion in debt. That's a lot of borrowed money sitting on top of a demand signal that may be partially manufactured by the very companies supplying the hardware.
SpaceX separately reported a $40 billion deal with Apollo Global Management to lease chips for AI data centers. Big numbers keep coming. But 'big number announced' and 'real underlying demand' are not the same sentence.
What this means for your planning
If your company is sizing an AI infrastructure investment — cloud GPU commitments, on-prem hardware, or a contract with a neocloud provider — the demand figures you're reading in the trade press are partially constructed from transactions like this one. That doesn't mean AI infrastructure spending is a bubble about to pop. It means the baseline you're using to justify your own spend deserves more scrutiny than it's getting.
Three things worth doing this week. First, if you have contracts with neocloud providers, check the counterparty risk clauses. Musk's 'guppy-level death' prediction may be self-serving noise, but CoreWeave losing a third of its value in a month while carrying $35 billion in debt is a concrete fact, not a prediction. Second, ask your cloud vendor or infrastructure partner directly: what share of their GPU capacity is contracted to customers with independent revenue, versus AI-native startups whose own funding depends on the same circular relationships? Third, if your board or CFO is using hyperscaler capex announcements as a proxy for AI adoption curves, flag that the Nvidia-Meta structure means some of those announcements are suppliers financing their own demand.
The counterargument I take seriously: Meta's scale is real, its AI products touch billions of users, and calling $95 billion in equity raises 'circular' understates how much genuine business value is being built. Fair. But my bet is that over the next two quarters, as neocloud consolidation accelerates and debt markets stay tight, the gap between announced AI infrastructure investment and actual end-user revenue will become impossible to ignore — and the companies that sized their plans to the announced figures will be the ones scrambling to explain the shortfall.